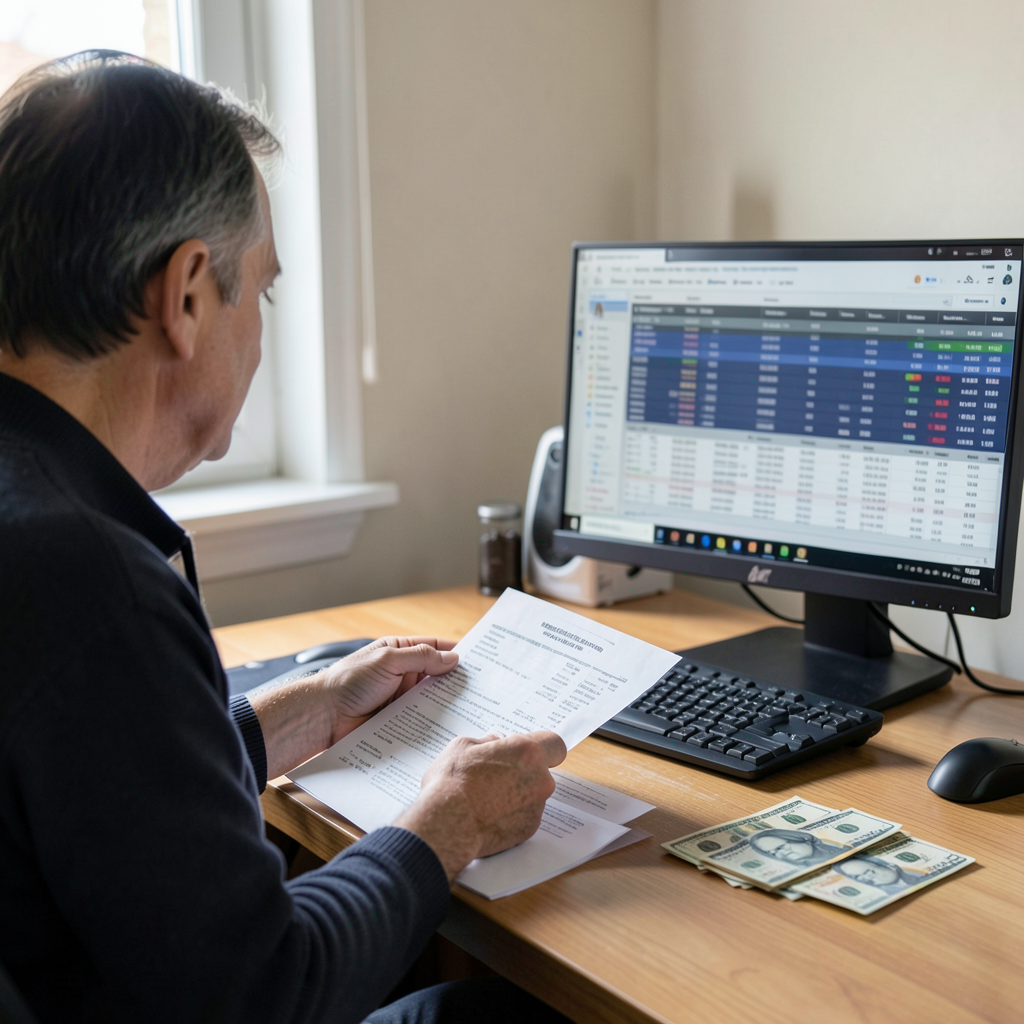
Research indicates that temporarily halting workplace pension payments could provide a modest short-term financial boost while significantly depleting retirement savings over time.
Analysis from Moneybox reveals that an average earner suspending pension contributions for a year could gain approximately £1,000 in immediate take-home pay, yet ultimately face a shortfall exceeding £12,000 in their retirement fund once lost employer contributions, tax relief, and compound investment growth are factored in.
Recent findings show that one in five adults in the United Kingdom have either stopped or are contemplating stopping their workplace pension contributions.
The changes are not solely driven by financial emergencies, as more than a quarter of adults, representing 27 percent, indicate they would reduce their pension savings simply to increase current disposable income.
The financial implications are substantial.
The projected £12,000 shortfall represents nearly a full year’s expenditure for an individual relying on a minimum retirement lifestyle, according to the most recent Retirement Living Standards.
This amount underscores how what appears to be a relatively small immediate gain could translate into considerable deprivation during retirement.
The appeal of additional immediate funds is understandable.
An extra £80 or £100 appearing in monthly pay represents visible, accessible money, whereas pension contributions constitute funds that may not be required for decades.
This distinction can make present consumption seem more attractive than future financial security.
Research conducted by Moneybox on the psychology of retirement identifies this tendency as present bias, where individuals assign greater worth to immediate rewards than to potentially larger benefits available at a later date.
Only 35 percent of British adults fully understand the significance of time and compound growth in building long-term pension wealth.
This limited awareness means numerous individuals may not recognise the consequences of suspending contributions, even for relatively brief periods.
The financial impact extends beyond the direct contributions deducted from salaries.
Depending on the specific pension scheme, reducing contributions could result in forfeiting employer matching contributions, tax relief benefits, and years of potential investment returns.
Brian Byrnes, Head of Personal Finance at Moneybox, explained that when household budgets are under strain, an additional £80 or £100 in monthly income can appear considerably more valuable than funds inaccessible for several decades.
However, the analysis demonstrates how imbalanced such a trade-off can become, with roughly £1,000 in extra take-home pay potentially resulting in more than £12,000 less in pension savings by retirement age once lost contributions and compound growth are incorporated.
He noted that current contributions represent only one element of the overall picture.
Individuals should locate any former workplace pension schemes and assess their performance and associated charges.
Consolidating older pension pots where suitable could simplify pension management and help ensure retirement savings are optimised for the future.
For households facing immediate financial pressures or essential expenditure requirements, accessing additional funds may be unavoidable.
Nevertheless, the figures demonstrate why those contemplating a suspension should fully understand what they might be surrendering.
Where feasible, any reduction should be treated as temporary, with contributions reassessed once financial circumstances improve.
Workers should also establish whether reducing contributions means relinquishing employer matching arrangements, as this could amplify the long-term cost of the decision considerably.
Individuals with legacy workplace pension schemes may benefit from reviewing where their funds are invested, the fees being charged, and how the underlying investments are performing.